Sunrate Gives AI a Corporate Card With a Very Short Leash
Sunrate launches an AI payment card with spending controls. Here’s how agentic business payments work, who benefits, and what a card limit cannot prevent.
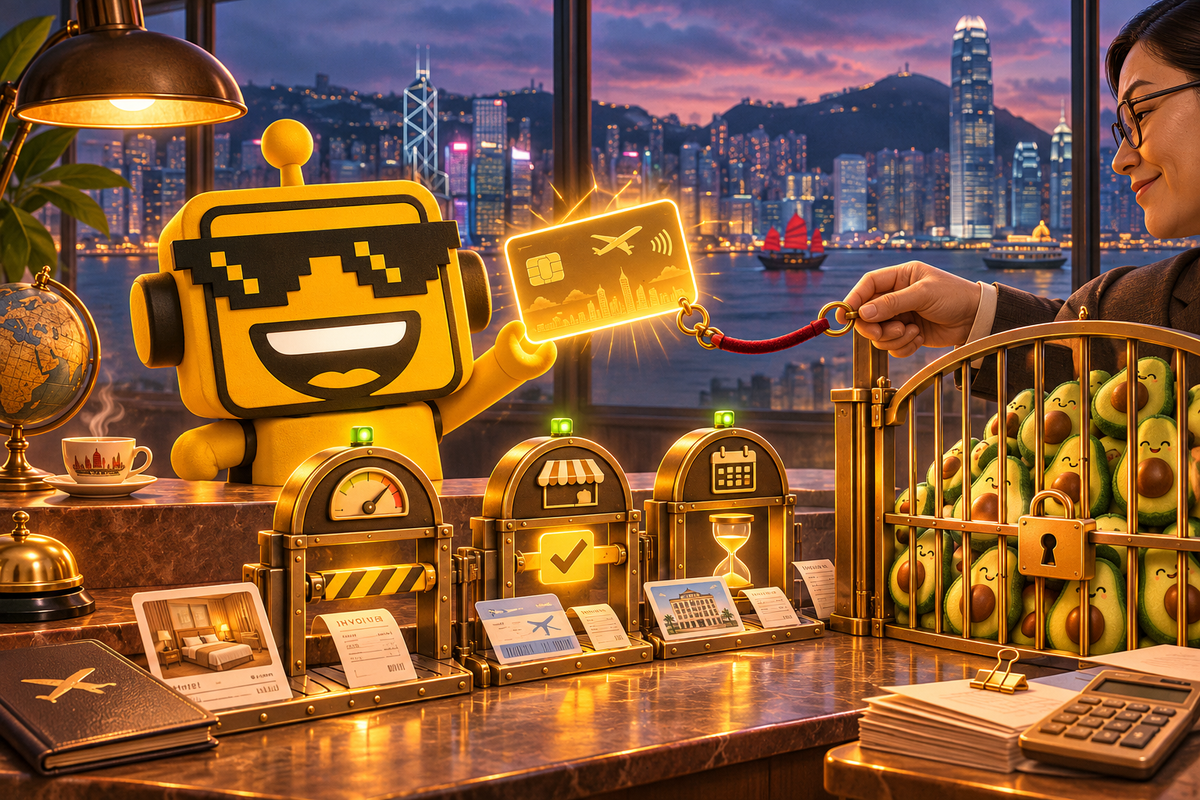
The AI has received a corporate card. Before anyone books it a leadership retreat, finance would like to discuss the spending limit, approved merchant categories, expiration date, and whether it actually needed whatever it just bought.
On November 2, Sunrate announced the launch of its Agentic Card at Hong Kong FinTech Week. The company describes a multi-currency virtual commercial card that authorized AI agents can create, manage, use for payments, and query for transaction results. Businesses set the permissions. Sunrate says the product has completed Mastercard Agent Pay certification.
This is a formal launch, not the first sighting of the name: Sunrate’s October 21 TourMind partnership announcement already mentioned its Agentic Card. Today’s material update is the launch and detailed description of the controlled payment workflow.
The distinction that matters commercially is just as specific. Software that recommends a purchase leaves someone else to execute it. Software with permission to pay enters the company’s control system. Its mistakes can now arrive with transaction references.
The card is virtual. The budget is regrettably real.
Sunrate says businesses can restrict spending by merchant category, amount, currency, geography, and validity period. Cards can expire after the assigned task. Actions are logged for audit, and exceptions can be blocked or sent for human review. Online travel agencies are one proposed early use case.
Consider a hypothetical travel company authorizing a $600 supplier payment. A tightly configured card could constrain the amount and permitted use. The agent would execute a bounded instruction instead of receiving an enduring invitation to explore the corporate balance sheet.
That is useful engineering. It separates the software’s ability to perform a task from unrestricted access to money. A temporary payment credential also gives the company a smaller, more legible object to supervise than an instruction such as “handle travel expenses efficiently.”
But the difference between a narrow rule and a broad wish is enormous. “Spend no more than $600” does not mean “purchase the correct booking.” It does not establish the correct dates, cancellation rights, or whether another system already paid. A perfectly authorized transaction can still be an impressively organized mistake.
Our guide to AI shopping agents examined this transition from recommendation to delegation. Business spending gives it a sharper edge: somebody has to reconcile the recommendation with the invoice, the approval, and the money that left.
Mastercard checks the badge, not the business case
Mastercard’s October explanation of agent identity describes verified credentials, tokenized payment information, spending controls, and evidence of user consent. Tokenization substitutes a payment token for the underlying card details. The objective is to help the parties recognize authorized agents and understand whose authority they carry.
These are important questions. A merchant should not have to infer that a bot is legitimate because its browser sounds confident. A business should be able to distinguish its own agent from something wearing the digital equivalent of a borrowed lanyard.
Still, Sunrate’s certification claim should not be inflated into a guarantee that every purchase is prudent or every AI decision correct. Identity, permission, and business judgment are different tests. Knowing which employee ordered the conference merchandise has never proved that the company needed 4,000 stress avocados.
That distinction also runs through Mastercard’s separate machine-payment initiative. Payment infrastructure can make delegated transactions recognizable and governable. The business still needs to decide what good delegation looks like.
The finance team gets promoted to rule writer
The attractive version of this product removes repetitive handoffs. A payment task comes with a clear purpose, sufficient documentation, an approved limit, and a defined route for exceptions. Software performs the routine steps while a person handles the unusual ones.
The less attractive version relocates the work. Finance spends its mornings tuning permissions, its afternoons investigating alerts, and its evenings explaining why the automated system needed twelve approvals to buy something the old system handled in three minutes.
Neither outcome is inevitable. The relevant measurement is total effort per correctly completed payment, including setup, review, corrections, and reconciliation. Counting automated actions alone would reward a system for creating unnecessary work with excellent throughput.
This is why BILL’s finance-AI controls were more interesting than another conversational interface. Authority has to be usable. A human nominally supervising a process needs enough information, enough time, and an effective way to stop it.
For a buyer evaluating Sunrate, the practical questions follow naturally. Can the agent modify its own limits? Which changes require independent approval? What happens when a payment succeeds but the response fails to arrive? How does the system prevent a retry from producing a duplicate? Who handles the exception after the card has expired?
Those are evaluation questions, not allegations that Sunrate lacks the answers. They are the difference between a compelling launch description and a workflow a finance team can responsibly depend on.
Everyone would like to sit next to the payment button
The incentives are straightforward. A business benefits if fewer people must shepherd routine payments. Sunrate benefits if its infrastructure becomes part of the operational workflow that generates those payments. Mastercard benefits if agent-driven commerce continues to use recognizable network credentials and controls.
My reading is that this is a distribution strategy as much as an AI feature. Once software can create the payment instrument inside the task, the payment provider sits closer to the moment spending is authorized. That position can become valuable even when the intelligence itself comes from elsewhere.
The launch release does not provide a price list, a jurisdiction-by-jurisdiction availability table, named Agentic Card customer results, or measured reductions in payment errors. Those omissions limit what we can conclude about adoption and economics. They do not erase the usefulness of the design.
As with our examination of whether AI agents actually make money, the credible opportunity is a bounded task with a measurable cost. The test is whether execution becomes cheaper and more reliable after supervision is included.
Sunrate’s sensible bet is that businesses will let software spend when the permission is specific enough. The card gets the agent through checkout. The leash is what might get it through procurement.