Bybit Adds U.S. Stocks. The Crypto Revolution Has Hired a Broker.
Bybit adds U.S. stocks and ETFs funded with USDC. Inside the Alpaca brokerage setup, trading costs and custody questions behind its latest fintech expansion.
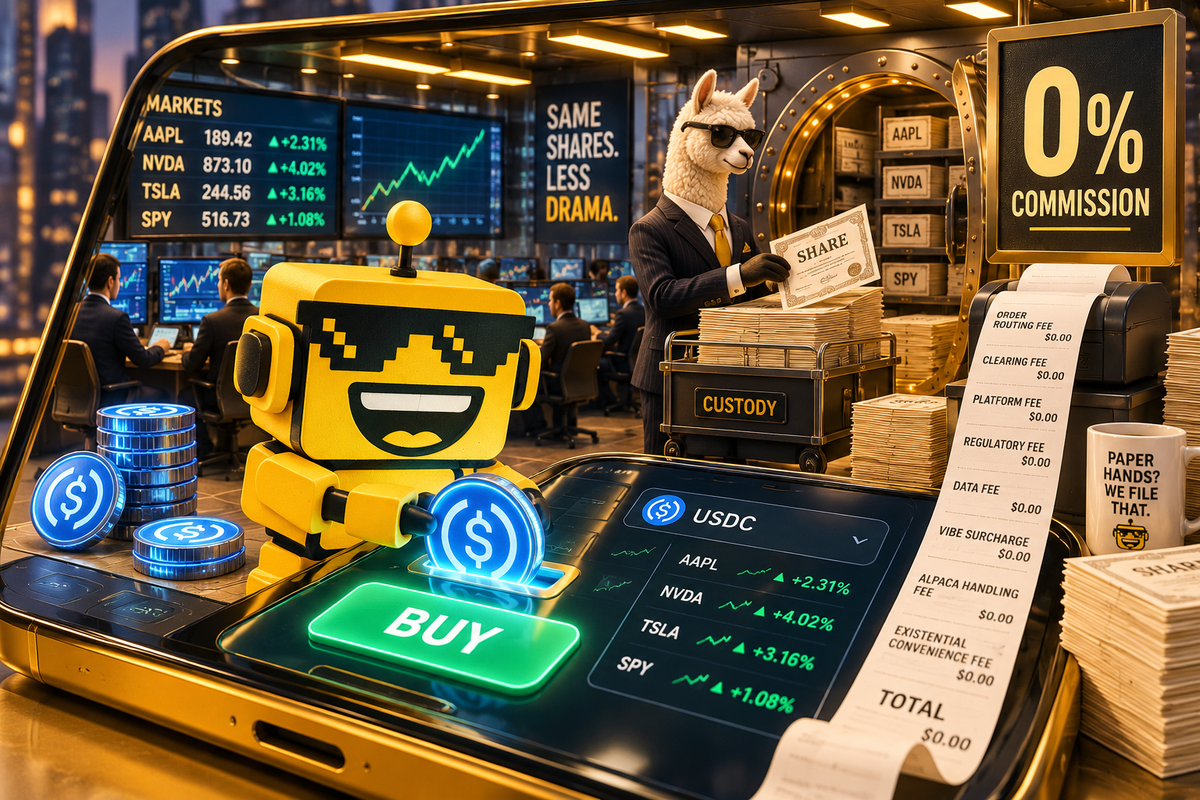
The crypto exchange has discovered a radical new financial instrument: a share in a company. There is a broker involved. Someone handles custody. Dividends require administration. The revolution has reached the stage where it needs a corporate-actions department.
On October 12, Bybit announced access to more than 1,000 U.S.-listed stocks and exchange-traded funds, purchasable with USDC by eligible, identity-verified users in permitted jurisdictions. Fractional holdings are available for eligible securities. Cash dividends are converted into USDC and credited to the user’s Unified Trading Account; voting rights are planned for a later phase.
Today’s hook is the public announcement, corroborated by contemporaneous Finance Magnates reporting. Product documentation appeared earlier, so this should not be mistaken for proof of the precise moment the first customer could trade.
The consequential move is giving a crypto customer another reason to keep money inside the same interface. Bybit gets a broader financial relationship. Customers get a potentially useful shortcut. Neither gets to abolish the distinction between a stablecoin balance and a securities account.
The buy button has a supply chain
Alpaca’s own October 12 announcement identifies Infra Capital Limited, regulated in Mauritius, as the investment dealer providing the products. Bybit’s disclosure describes Infra as the introducing broker and Alpaca Securities as the provider of U.S. clearing, settlement and custody. Alpaca also executes the orders.
In plain English, the familiar app is the storefront. Behind it are businesses responsible for getting a trade executed, completing the exchange of money and securities, and holding the assets. A single login is a user-experience achievement. It is not a corporate merger of everyone’s obligations.
That can be a sensible arrangement. Building every component yourself is expensive, and specialist infrastructure can let a consumer platform add a service without pretending to be the entire capital market. The bargain works when responsibilities stay legible after the marketing has finished simplifying them.
It is the same question raised by Modern Treasury’s pursuit of a custody-focused bank charter: moving an asset and safeguarding it are separate jobs, even when software makes them look adjacent.
A ticker symbol is not a legal description
Bybit describes this product as an economic interest in the underlying securities, rather than a derivative tracking their prices. That distinction deserves more attention than the size of the stock menu.
A Bybit comparison published today separates real equities from contracts for difference and perpetual contracts. Those other instruments can provide stock-price exposure without the same ownership relationship. The fact that multiple products display a recognizable company ticker does not make them interchangeable.
Imagine a customer who wants a small position in a technology company. The useful questions are what instrument they bought, which entity owes them what, how distributions work, and how they can exit. “It went up when the company’s shares went up” answers remarkably few of those questions.
USDC is the funding route here. Paying with a token does not, by itself, turn the purchased share into a freely transferable blockchain asset. That is a useful antidote to the tendency to describe every meeting between crypto and equities as tokenization, then allow the noun to do several lawyers’ worth of work.
Zero commission still needs a receipt
The announcement advertises zero trading commission. That phrase needs its usual financial-services seat belt.
Bybit’s product comparison page separately lists a 0.5 USDC small-order charge for trades of $500 or less and a 10-basis-point trading spread for trades of $500 or more. Ten basis points means 0.1%. The page overlaps its categories at exactly $500, which is a reason to inspect the actual order quote rather than treat a marketing summary as a definitive invoice.
Using that page’s small-order figure, a $50 trade would carry a charge equal to 1% of the amount invested, before any movement in the stock price. That is arithmetic, not an allegation of hidden losses. It illustrates why the distinction between “commission” and “cost” matters most to the people attracted by small investment minimums.
A clearly disclosed charge can be perfectly reasonable. A customer may willingly pay for convenience. But the comparison should be between total costs and useful capabilities, not between one provider’s enormous zero and another provider’s smaller print.
The market can stay awake and still be thin
Bybit advertises 24/5 trading, subject to availability. Wider hours are useful for users whose lives do not follow New York’s office clock. They are not a promise that every session has the same depth.
The SEC’s extended-hours investor bulletin explains the tradeoffs: fewer willing buyers and sellers, potentially wider gaps between bid and ask prices, greater volatility, and differences among trading systems. An app can accept your attention around the clock more easily than a market can manufacture someone willing to take the other side at an attractive price.
Custody protection also has boundaries. SIPC explains that its protection concerns eligible customer assets when a member brokerage fails and SIPC intervenes; it does not cover market losses. Alpaca’s membership should not be read as a blanket guarantee for every asset or relationship visible inside Bybit. Account structure and applicable terms matter.
The screen can consolidate balances. It cannot consolidate away their different risks.
Keeping the customer is the actual asset class
My reading of the business incentive is simple: if customers can buy equities without leaving, Bybit has fewer reasons to watch them move their financial lives elsewhere. Alpaca gains another distribution relationship. Users who already hold USDC may gain a more convenient path to an investment they wanted anyway.
That fits the pattern in SoFi’s integration with Kraken: financial platforms increasingly compete over the transitions between products. And as with Coinbase and PPRO’s stablecoin checkout work, the strongest case for the technology is often reducing a practical handoff rather than demanding that everyone adopt a new financial identity.
The test is whether those saved steps come with clear costs, understandable ownership and competent support when something breaks. A super-app that makes those things easier has built something useful. A super-app that merely puts incompatible assumptions beside each other has built a very attractive customer-service queue.
Bybit’s announcement is a credible distribution story, not evidence that securities infrastructure has become obsolete. The crypto revolution has hired a broker. Now it should make sure the customer knows which desk to call.