Usio Lands Inside Utility Billing. Your Water Bill Has a Payments Strategy.
Usio's Harris partnership embeds payments in utility billing software. We examine the business incentives, rollout questions, and what customers actually gain.
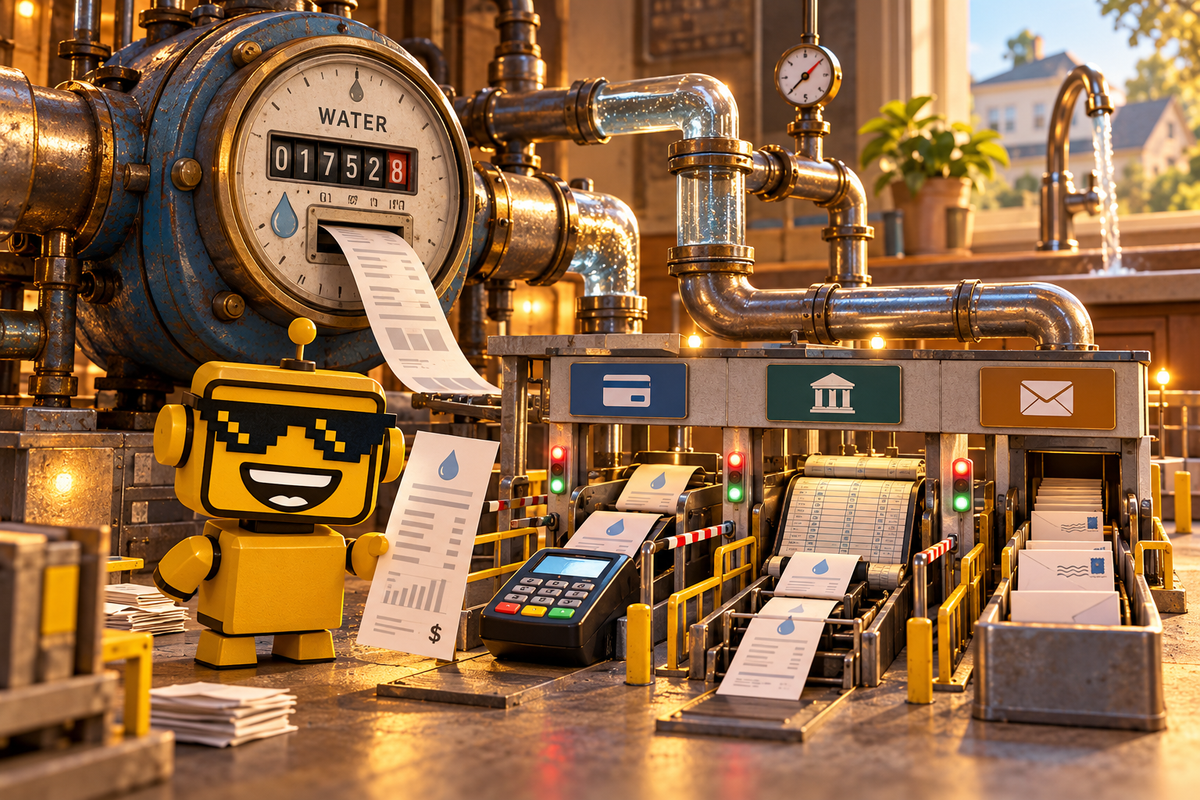
Your water bill has apparently been underperforming as a fintech distribution channel. Fortunately, someone has assembled a partnership to address this missed opportunity.
On September 29, Usio announced an agreement with Harris Computer Corporation to become a preferred payment-services provider. Harris will integrate Usio into its utility customer information system, with utilities adopting the payment module receiving card, ACH and PINless debit processing. The announcement also includes physical check and statement printing and distribution.
This is an announced integration, not evidence that every Harris utility customer switched processors this morning. The release does not provide a deployment calendar, contracted processing volume, named live utility, or consumer fee schedule.
Still, it is a revealing fintech story. Instead of persuading households to download another app, a processor can reach them through the software their biller already uses. The prize is a recurring financial chore. Nobody needs to become emotionally invested in a payment brand. They just need the balance to say zero.
The customer information system knows where you live
A customer information system, or CIS, connects the customer account to billing and service records. In utility software, that can mean linking a person, a property, meter readings, amounts owed and payments received. The checkout screen is only the visible edge.
Harris ERP's existing CitySuite utility-billing documentation illustrates the category: account management, billing, cash receipting, collections and customer access sit together. It describes splitting payments, paying several accounts with one remittance, and posting accounting entries. These are background examples of Harris software capabilities, not confirmation that CitySuite is the specific product or first deployment covered by today's agreement.
Consider a hypothetical resident paying a $92 water bill. Accepting the payment is one task. Connecting it to the correct service address, updating the balance and giving the customer-service desk a usable record are separate tasks. If the payment succeeds but the account still looks delinquent, the impressive part of the transaction has happened somewhere the resident cannot see.
The integration opportunity is to reduce those gaps. In a successful implementation, the resident encounters a dull, reliable receipt. That is a higher product standard than it sounds.
Embedded finance means someone else found the customer
Usio's strategy has an established foundation. Its first-quarter 2025 filing describes its payment-facilitation platform as targeting software developers in bill-oriented industries, including utilities. The platform combines merchant enrollment and different payment capabilities through an API: a structured interface that lets one software system request actions from another.
The commercial logic is straightforward. Software already occupies the workflow where a bill becomes payable. Adding payment processing puts a financial service beside existing demand. A processor does not have to create the household's need to pay for water. Civilization has taken care of customer acquisition.
For Usio, the prospective benefit is distribution through Harris. For Harris, integrated payments can make its software more useful and harder to replace. For utilities, the prospective benefit is fewer operational seams. These are incentives, not disclosed revenue forecasts; the companies have not published the economics of their agreement.
It is a different route toward the control we examined in TabaPay's planned bank acquisition. One strategy moves closer to the regulated institutions beneath payments. This one moves closer to the software that originates the payment demand. Both make more sense once you stop treating the button as the whole business.
One interface does not make every payment identical
Usio's developer-documentation directory is a useful antidote to frictionless-payment poetry. Alongside checkout and enrollment interfaces, it lists ACH return codes, rejected-file specifications, pending-file formats and a processing schedule.
That is what an operating payment service looks like: instructions, exceptions and records. ACH moves funds between bank accounts. Card payments use different networks and operational rules. Giving customers both choices does not make those systems behave identically.
Imagine the same $92 payment encountering a processing problem after the customer has left the website. My evaluation would start with what the billing system displays, whether the resident receives a clear explanation, and whether a staff member can trace the original attempt without requesting three screenshots and a small act of faith.
Those are design questions, not allegations about either company's performance. They are also where integration earns its keep. Our coverage of IPID's recipient-verification business explored a neighboring distinction: instructing money to move and establishing what the instruction means are separate jobs. Utility payments add another: making sure the biller's record tells the same story as the payment system.
The customer benefit needs its own receipt
A utility can gain operational efficiency without every saving reaching the household. A resident can gain another way to pay without gaining a cheaper one. Those outcomes need to be measured separately.
I would judge an actual deployment by the total cost of each payment choice, the clarity of receipts, the handling of failed attempts, and how easily someone can reach a human who can fix a mismatch. A shorter procurement presentation is useful to the procurement team. It is not a consumer outcome.
The inclusion of paper services is also sensible. A payment operation has to accommodate the channels people use, including ones that make a product designer stare mournfully at an envelope. Modernizing the connection between systems need not require every customer to modernize their habits on command.
There is a related lesson in PayPal's addition of Pix in Brazil: payment providers become more useful when they fit the environment in which customers already transact. The context determines the product. The logo does not get a deciding vote.
The fintech revolution has a service address
My reading of this agreement is that the attractive asset is proximity to recurring bills. That makes the announcement more interesting than its corporate vocabulary suggests, while leaving plenty for an implementation to prove.
We have examined the same contest for distribution in our guide to stablecoin payment infrastructure. Usio's utility pitch reaches familiar strategic territory through ordinary billing software: get embedded where money already needs to move, then make the connection useful enough to keep.
The fair verdict is conditional optimism. Better integration could save staff time and spare residents the peculiar indignity of proving they paid a bill to the organization that collected it. The proof will be working deployments and understandable customer outcomes.
Your water bill now has a payments strategy. Ideally, the next innovation will be that you never have to think about it.