BNY Brings Crypto Custody to Europe. The Revolution Has a Filing Cabinet.
BNY expands crypto custody in Europe under MiCA. What institutional safekeeping protects, what it cannot fix, and why banks want the keys to digital assets.
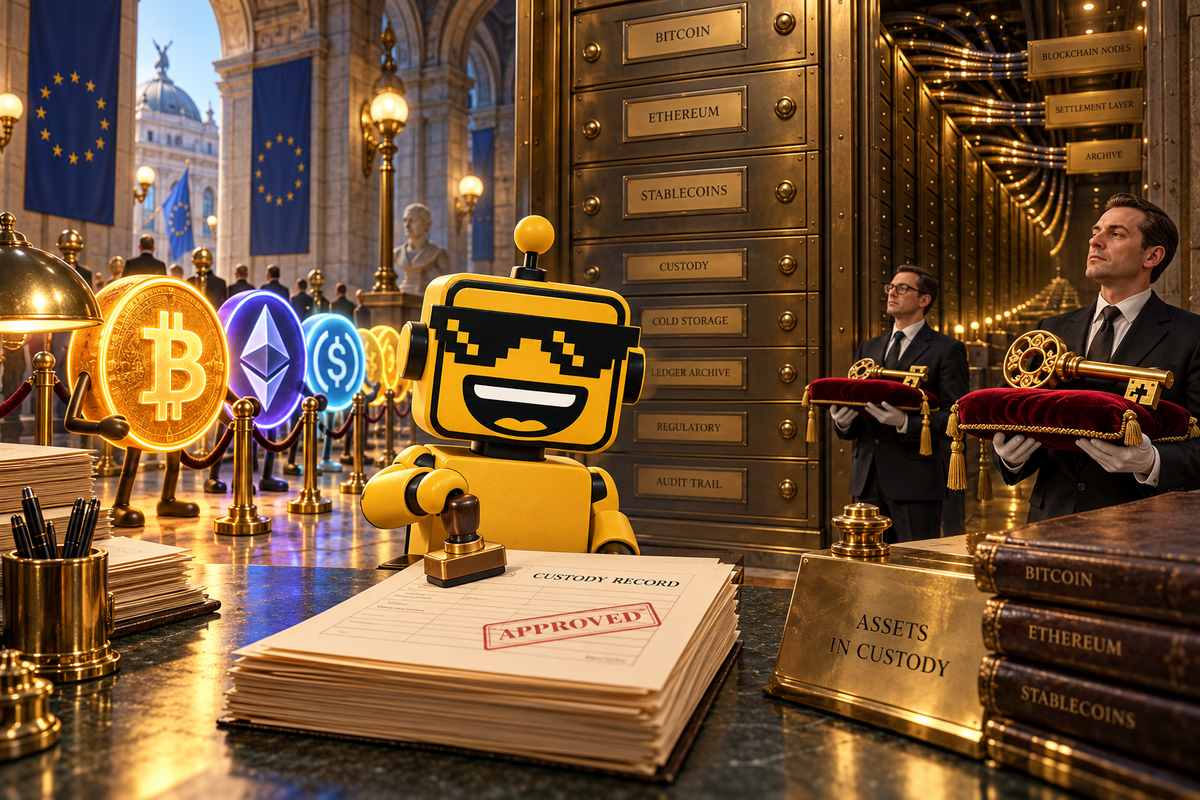
The next phase of institutional crypto appears to involve fewer declarations of independence and more people asking who is authorized to sign the withdrawal request. BNY would like to handle that conversation. Ideally, along with the assets.
This week, BNY announced the expansion of its Digital Asset Custody platform for select institutions in the European Union under the Markets in Crypto-Assets framework, or MiCA. The bank says its European entity, The Bank of New York Mellon SA/NV, joined ESMA’s MiCA register in July. Today’s news is the expansion announcement; the registration is earlier groundwork.
That distinction matters. This is neither a newly invented blockchain nor an invitation for everyone in Europe to open a crypto account. It is an established custody business extending its digital offering into a regulated institutional market. The revolution has reached the stage where someone needs a vendor agreement.
Someone has to keep the keys
Crypto custody means safeguarding the assets, or the means of accessing them, for a client. The coins do not physically migrate into a bank vault. The operational problem is controlling who can authorize transactions, keeping that access secure, and maintaining records that establish what belongs to whom.
A private key is the cryptographic secret used to authorize transactions. Lose control of that capability and the consequences can be rather more permanent than forgetting your expense-system password. Institutional custody turns that responsibility into a service with security procedures, contractual duties and reporting.
BNY says its platform, originally launched in 2022, uses multiparty computation, segregated client wallets and private-key storage. Its announcement lists BTC, ETH, SOL and USDC among the assets accessible through its custody model, with broader support an ambition. It does not provide a complete EU client eligibility matrix or fee schedule.
Those details should keep the sales pitch grounded. A list of supported assets is useful. It is not proof that every institution can immediately use every asset in every proposed workflow.
Consider a hypothetical investment manager holding crypto for a fund. It needs to know who approves transfers, how holdings reconcile with its records, and how it recovers access during an operational incident. “The blockchain is transparent” answers remarkably few of those questions. Transparency is lovely; an authorized signatory is also helpful.
MiCA brings a contract to the group chat
The regulatory layer is substantive. MiCA’s safeguarding provisions require providers holding client crypto-assets or their means of access to protect clients’ ownership rights, including in insolvency, and prevent use of those assets for the provider’s own account. That is a meaningful constraint on what a custodian can do with things it does not own.
Article 75 adds custody-specific obligations: an agreement defining responsibilities and charges, client position records, custody policies, and legal and operational separation from the provider’s own estate. It also establishes liability for losses attributable to the provider, capped at the asset’s market value when the loss occurred.
The qualification matters. The rule does not make the custodian responsible for every possible blockchain failure. It distinguishes attributable incidents from events the provider can demonstrate occurred independently of its service or operations, including certain underlying ledger problems outside its control.
This is what financial infrastructure looks like when the difficult bits are spelled out. Who has the asset? Who can move it? Who owes whom after a failure? The answers are less shareable than a laser-eyed profile picture, but considerably more useful in a dispute.
A better vault does not improve the thing inside
The temptation is to hear “bank” and “regulated” and conclude that the investment itself has become safe. That leap deserves to be stopped at reception.
A custodian can preserve the number of tokens you own while their market value falls. It can perform its safeguarding job properly while an issuer or a market creates a separate problem. Operational security and investment quality are different questions, even when they appear on the same dashboard.
The European supervisory authorities’ consumer explanation of MiCA is useful context here: protections depend on the asset and service involved, and services outside the regulatory framework can offer limited or no protection. Regulation is a set of defined obligations, not a force field.
For the institutional buyer, the practical exercise is therefore contractual. Which assets and networks are covered? How are transfers approved? What happens during an outage? Which party carries each risk? A polished interface can make those questions easier to manage. It cannot make them disappear.
Our guide to stablecoins as financial infrastructure explores the same distinction between useful software and the legal relationships underneath it. The balance on the screen is only the beginning of the explanation.
The bank would like the relationship, please
The strategic logic is straightforward. If an institution starts using digital assets, its existing service providers face a choice: support the new activity or let another company become indispensable. Custody is an attractive place to remain relevant because assets need somewhere to be held before, during and after the exciting transaction.
That is analysis of the incentive, not a disclosed revenue forecast. BNY’s release does not establish how much this European expansion will earn or how quickly clients will adopt it. The opportunity is to connect digital activity with existing institutional operations. Whether that connection is convenient enough to win business remains the commercial test.
It also explains why fintech companies approach the same problem from the opposite direction. Modern Treasury’s pursuit of a national trust bank charter is about adding a supervised custody layer around money-moving software. BNY starts with the institutional banking relationship and extends toward digital assets. Different starting points, similar interest in the place where money waits.
The surrounding services remain separate jobs. Our coverage of SoFi and Kraken’s infrastructure arrangement shows how banking, trading liquidity and settlement fit together without becoming interchangeable. Holding an asset securely does not automatically give it a liquid market or make every payment route work.
Institutional adoption comes with an operations manual
The broader signal is that banks see digital finance as work they can absorb. SiliconSnark’s look at banks’ interest in tokenized deposits describes another version of that instinct: retain the customer relationship while changing the technology used to serve it.
BNY’s expansion is credible evidence of that direction, not evidence that every proposed crypto use case now makes economic sense. The next useful information will be mundane: actual client adoption, supported workflows, operating reliability and costs. Those details will tell us more than another industry declaration that finance has entered a new era.
There is something quietly encouraging about this. Institutional crypto becomes more useful when someone can explain its responsibilities without reaching for a manifesto. BNY is offering to be that someone. The filing cabinet may be less photogenic than the revolution, but at least it has a place for the withdrawal policy.