Circle Funds Stablecoin Aid Payments. The Revolution Needs an Accounting Department.
Circle Foundation is backing UNDP and WFP stablecoin payment work. The test is whether faster settlement delivers cheaper, usable aid to people who need it.
The most encouraging phrase in a crypto announcement this week might be “treasury and reconciliation systems.” Somewhere, a conference organizer has just canceled the laser show.
This week, Circle Foundation, UNDP and the World Food Programme announced two digital-payment initiatives. A grant will help UNDP establish a Digital Asset Innovation Pool for regulated stablecoin use. A separate grant to World Food Program USA supports WFP’s payment infrastructure, including governance, reconciliation, compliance and local-provider integration. WFP plans to test two to three country corridors over three years.
The announcement does not disclose grant amounts or name the planned corridors. It does not establish an exclusive USDC deployment. UNDP’s mechanism is intended to supplement banking channels where they present barriers, not replace them.
That is a promisingly restrained proposition. My read is that the interesting product here is operational competence: can a different way of moving money improve aid delivery after every conversion, delay and support problem has been counted?
A Dollar Token Cannot Buy Dinner by Itself
A stablecoin is a token designed to maintain a reference value, often one dollar. Circle describes USDC as backed by cash and cash-equivalent reserves and redeemable one-for-one. Its direct redemption service, Circle Mint, serves eligible institutions; individuals generally use exchanges, wallets or other providers. That distinction explains why “digital dollars” and “dollars I can spend here” are different stages of a payment.
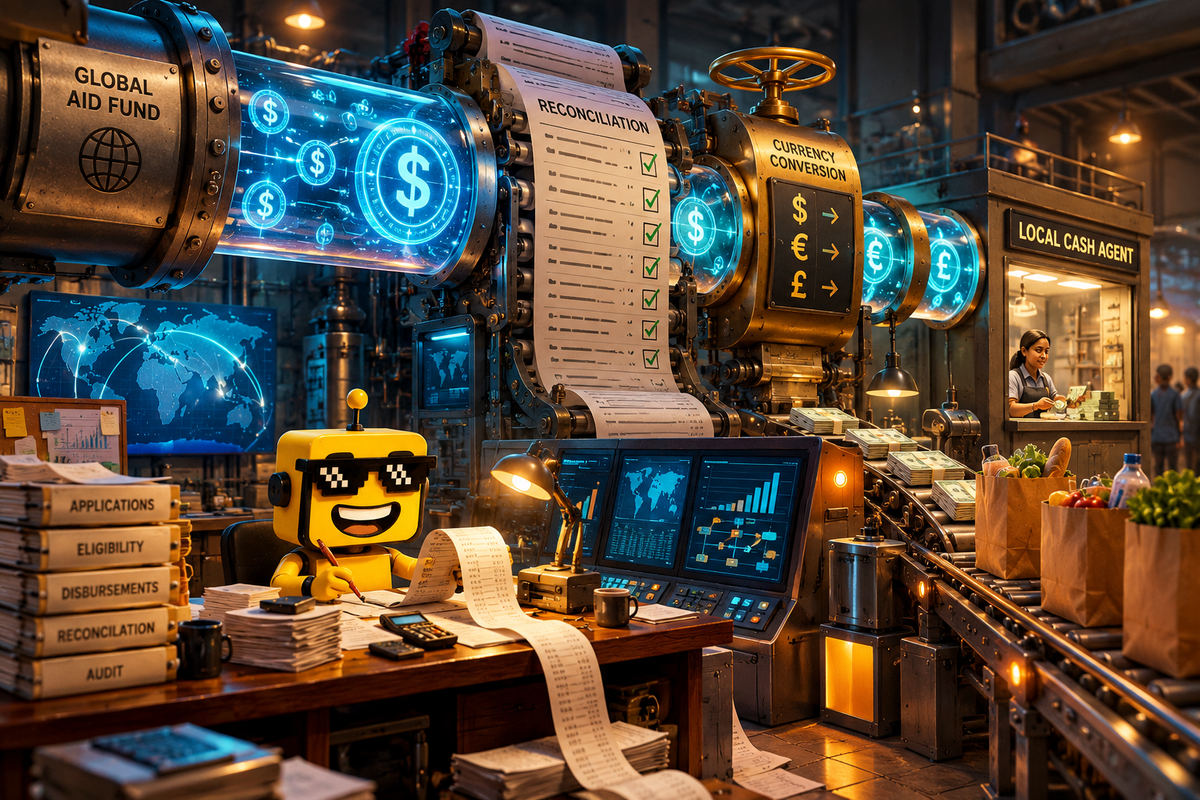
Consider a hypothetical aid organization sending $100 to a household. A provider could move the value using a stablecoin, then another provider could convert it into local currency and credit a mobile wallet. The household might never see a token. That would be perfectly fine. People receiving assistance should not need an opinion about blockchain architecture before buying groceries.
But each transition matters. Who supplies the local currency? What exchange rate applies? Can the recipient withdraw cash nearby? If the wallet receives the money immediately but the cash agent cannot pay out until tomorrow, the useful arrival time is tomorrow.
This is the same practical issue behind Circle’s agreement to acquire Tazapay: a fast token still needs dependable connections to existing financial systems. The difference is that humanitarian recipients have particularly little room to absorb a provider’s learning experience.
The Existing System Is More Than a Wire Transfer
WFP explains that cash assistance is useful where markets function but people cannot afford necessities. It gives recipients choices and can support local businesses. WFP reports $2 billion in cash-based transfers in 2025. That provides some perspective: this is an established delivery model evaluating another payment tool, not a crypto company inventing the concept of giving people money.
Nor is blockchain new to WFP. Its Building Blocks system uses a privately managed blockchain network to help organizations coordinate assistance. Participating organizations share ownership and management. That is different from assuming that every recipient should hold a publicly traded digital token.
The distinction is useful because “uses blockchain” can describe quite different things: sharing records among aid agencies, settling an institutional payment, or handing someone a wallet balance. Each solves a different problem. Each also creates different responsibilities when something goes wrong.
SiliconSnark’s coverage of Circle’s Arc launch examined infrastructure designed to make blockchain costs more legible. Aid delivery demands an even stricter version of that test. A finance team needs to explain where the money went; a recipient needs to use it. Both statements must be true simultaneously.
The Risk Department Is Part of the Product
The word “regulated” deserves attention, but it cannot do every job in the sentence. For a concrete example, Circle’s USDC terms describe address-blocking powers, operational interruptions and possible redemption delays. They also state that USDC in Circle Mint is not protected by deposit insurance. These are existing product conditions, not newly announced restrictions on the aid programmes. The distinction also runs through our coverage of SoFi’s bank-issued stablecoin and Kraken partnership: the institution behind a token and the protections attached to the token are separate questions.
The operational lesson is straightforward: a programme needs a way to handle failures before it depends on the payment route. If a transfer is delayed, who tells the recipient? If a provider freezes an account for review, who resolves it? If an exchange rate moves between authorization and payout, who absorbs the difference?
These questions are not arguments for preserving expensive transfers forever. They are how a potentially better payment method becomes safe enough to use. Fast delivery has value. So does a competent person who can explain why a payment is missing.
The recipient check matters too. Our coverage of IPID’s payee-verification business explored the gap between moving money quickly and establishing where it should go. A new settlement method does not make that gap disappear. It changes where the checks must happen.
Measure the Receipt, Not the Demo
I would judge these trials against the best available local alternative, with the same recipients and comparable conditions. Compare total cost, including currency conversion and cash withdrawal. Measure time until funds are usable. Count failed payments and the hours staff spend fixing them. Record how many people cannot access the service at all.
One illustrative result could be a cheaper international transfer followed by an expensive withdrawal. Another could be a slightly higher processing cost that delivers usable money a day sooner. Neither fits neatly into “blockchain wins” or “blockchain loses.” Both could inform a serious procurement decision.
Circle also has a clear strategic incentive. Successful humanitarian use could strengthen the case for the wider stablecoin category and the infrastructure businesses around it. That does not invalidate the work. It makes independent measurement especially valuable. The useful evidence should include places where conventional payments remain the better option.
The best outcome would be almost invisible to recipients: assistance arrives sooner, costs less to access, and comes with a reliable route for resolving problems. No wallet tutorial required. No ceremonial conversion of human need into a crypto adoption statistic.
Circle Foundation is funding a worthwhile question. The answer should be written in usable money delivered, rather than transactions celebrated. If the revolution needs an accounting department to get there, give the accounting department the good chairs.